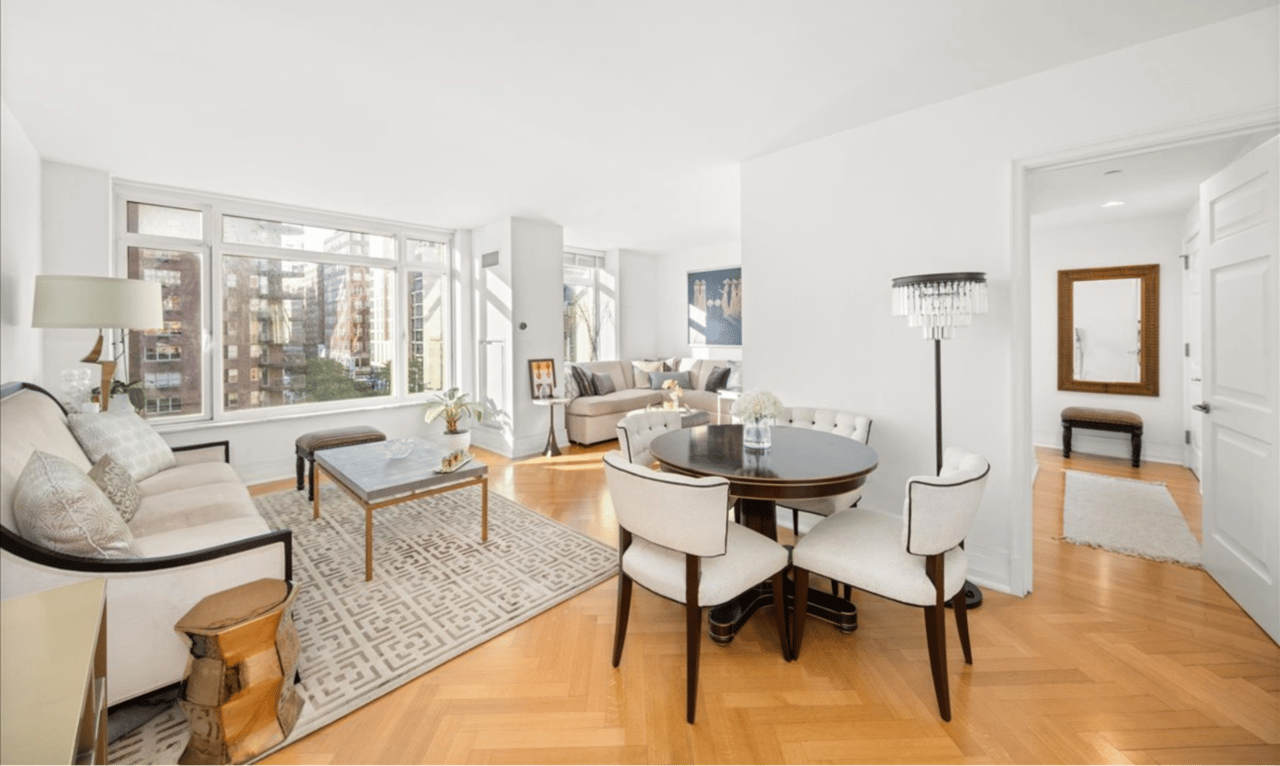
In April 2026, a two-bedroom of about 2,500 square feet at 15 Central Park West closed for $10.8 million, just under its last asking price. According to The Real Deal, the seller's LLC had bought the apartment in 2014 for $13.1 million. City transfer records show that the same apartment, unit 15K, first sold from the sponsor in December 2007 for about $4.9 million. So one apartment produced two owners with opposite results. The first more than doubled their money on paper. The second sold for roughly $2.3 million less than they paid after about twelve years.
That pair is a fair summary of the building's resale record. The limestone tower at West 61st Street has a reputation for holding value, and many sales back it up. Read the 2025 and 2026 closings by the year each seller bought, though, and the reputation mostly belongs to one group of owners. Sponsor buyers from 2007 and 2008 have done very well. Owners who bought on the resale market in the mid-2010s have mostly sold below their purchase price. For someone shopping at 15 CPW now, the address tells you less than the price you pay relative to where the cycle stands.
The 2025–26 closings, grouped by purchase year
These are resales that recorded between February 2025 and July 2026, with each seller's purchase price. The three 2008 purchases come from deals The Real Deal reported. The rest come from New York City Department of Finance transfer records.
| Apartment | Seller bought | Seller paid | Resold | Resale price |
|---|---|---|---|---|
| 27D | 2007 | $8.88 million | April 2026 | $21.95 million |
| 12C | 2007 | $14.15 million | March 2026 | $25.13 million |
| 29A | 2008 | $10.5 million | December 2025 | $22 million |
| 14B, with storage | 2008 | $15.5 million | February 2026 | $24.8 million |
| Condo plus studio | 2008 | about $6.6 million combined | December 2025 | just under $20 million |
| 12L | 2014 | $9.5 million | February 2025 | $6.8 million |
| 15K | 2014 | $13.1 million | April 2026 | $10.8 million |
| 2B | 2016 | $5.3 million | April 2026 | $4.4 million |
| 8B | 2017 | $21.5 million | June 2026 | $21 million |
The Real Deal put the $22 million sale of 29A in December 2025 at nearly $7,100 a square foot, against the seller's $10.5 million purchase in 2008. In February 2026 the outlet reported a four-bedroom of about 3,400 square feet that traded with a storage unit for $24.8 million. The seller had bought the package in 2008 for $15.5 million, and the apartment had first been listed in May 2024 at $27.5 million. A December 2025 sale of a condo plus a studio suite for just under $20 million, also reported by The Real Deal, replaced a 2008 purchase of $5.7 million for the condo and about $905,000 for the studio.
All of these are nominal results on recorded prices. They are not adjusted for inflation or reduced by carrying costs, transfer taxes or commissions. Even so, the split in the table is clean. Every seller who bought from the sponsor came out well ahead. Every seller who bought between 2014 and 2017 sold for less.
Three apartments, three owners each
The clearest evidence is in apartments that have now had three owners. Unit 12L sold from the sponsor in December 2007 for about $4.44 million, resold in August 2014 for $9.5 million, and sold again in February 2025 for $6.8 million. Unit 8B went from about $11.15 million in December 2007 to $21.5 million in December 2017, then sold for $21 million in June 2026. Unit 2B sold for about $3.71 million in 2008 and $5.3 million in 2016, then for $4.4 million in April 2026.
In each case the apartment is worth more today than when the building opened. The appreciation exists. It went to whoever owned the unit while prices rose toward the 2014–2017 peak. Each later buyer paid a price that already included that rise and then sat through a decade in which it did not continue.
Nothing went wrong with these apartments. The 8B owner sold for about 2% below a purchase made at the top of the last cycle, which is a mild outcome for a $21 million apartment. A buyer who paid near the peak simply had no gain to collect.
One more data point runs the other way. Unit 11L sold for $6 million in March 2025 and again for $6.995 million in June 2026, a gain of almost $1 million in about fifteen months. A buyer whose entry was close to the current market got the same lift the sponsor buyers had in their early years.
Same floor, very different prices per foot
Purchase year is the main variable. The apartment itself is the second, and the gap is wide. In the 2025–26 closings, prices ranged from about $2,889 a square foot for a 1,343-square-foot unit, 16H, to about $7,508 a square foot for 12C, a 3,347-square-foot residence that sold in March 2026. Both 12C and 12L are on the twelfth floor. About fourteen months apart, 12L closed at about $3,532 a square foot and 12C at more than twice that.
The high per-foot sales are the large park-facing residences. When the New York Post covered two contracts that topped the city's luxury market in December 2025, the more expensive was a three-bedroom of 3,347 square feet with Central Park views from the living room, dining room and office, last asking $26.8 million. According to the Post, it was the first time since 2020 that the week's two top contracts in the Olshan Luxury Market Report came from the same building.
So a 15 CPW buyer in 2026 is really making two separate bets. One is on the building, which has a long record of attracting buyers. The other is on a specific line, floor and exposure inside it, and that bet has a much wider range of results than the building's average implies.
How this compares with Billionaires' Row
The usual comparison is with the newer supertall towers a few blocks south. In August 2025, The Real Deal compared sponsor prices with first resales at five Billionaires' Row buildings. It found an average gain of 43% at 220 Central Park South, 2.3% at 432 Park Avenue, a 16.6% loss at 111 West 57th Street and a 24.2% loss at One57. Appraiser Jonathan Miller told the outlet that the boom was a "you had to be there" moment.
The study did not include 15 CPW. The sponsor-buyer gains in the table above are well beyond anything it measured outside 220 Central Park South, another Robert A.M. Stern building. The same piece carried a caution from Donna Olshan of Olshan Realty: "Very often, the price that's recorded is not the actual price," because sponsors may give concessions at closing. That cuts both ways. It can inflate a building's apparent losses, and it can shrink its apparent gains.
On Billionaires' Row, the buyers who lost money were the first buyers, who paid peak prices for brand-new product. At 15 CPW, the first buyers came in early in the cycle and the later resale buyers paid the peak. In both places, the loss sits with whoever paid the top price.
What a price paid in 2026 is buying
Robert A.M. Stern died on Thanksgiving Day last year, which brought the building fresh attention, including the run of $20 million-plus deals the Post covered that December. Miller told the New York Post he did not see Stern's death "pushing values in his building up overnight," but that "the lack of future Stern projects will help sustain the premium they already achieve." A premium that holds steady is useful to a seller. A buyer pays it at the start.
The current market fits that reading. In mid-November 2026, a full-floor offering, 16/17B, is asking $40 million after a $5 million cut in September, and 31B was reduced on November 10 to $15.385 million. Unit 37C went into contract on October 31. The 14B sale that recorded in February also shows the pattern: it was first listed in May 2024 at $27.5 million and traded for $24.8 million. Sellers who bought in 2008 can accept those discounts and still come out far ahead. Their asking prices are not tied to what they paid, and that gives them room to negotiate.
For a buyer, the 2014 owners of 12L and 15K are the useful precedent. Both bought apartments in a building whose reputation was already established, at prices that already reflected it. A buyer at 15 CPW today should test the price against the most recent closings for the same line and exposure, not against the building's long-run average or its best sales. Kane Manera of Corcoran told The Real Deal that a hold of five to seven years or more is the right horizon for trophy property. The 2014–2017 buyers held longer than that and still sold at a loss, so the hold period could not make up for the purchase price.
For owners, the same split applies. A sponsor-era owner can treat the building's reputation as banked equity. An owner who bought near the peak has a different pricing problem, and the most recent closings in comparable lines are a better guide to it than the building's headlines. Our earlier comparison of co-op and condo ownership on Central Park West covers how condo buildings like this one trade differently from the co-ops along the avenue, and our strategy notes for Central Park West sellers cover listing preparation.
If you are weighing an offer at 15 Central Park West or deciding when to list there, Kobi Lahav can compare your specific line and floor against the building's recorded resales and show where your purchase price falls in the cycle. You can request a valuation or browse the Central Park West neighborhood guide, then Contact Kobi.